Protect what you've built for retirement.

Annuities and max-funded IULs, explained in plain English by a licensed agent. No pressure, and no cost to talk.

Licensed producerNPN 21767258
30+ national carriersAccess through one agent
No cost to talkNo fee for the review
Plain EnglishNo jargon, no pressure
Where your money sits

Every place to keep retirement money has a trade-off.

Here's how the three most common ones compare, so you can see what an annuity does and what it costs you.

In the market

401(k), IRA or brokerage invested in stocks and funds

If the market drops
Your balance drops with it.
Growth
No ceiling, and no floor.
Getting to your money
Usually easy to reach, subject to your plan's and the IRS's rules.
The catch
A big loss right before or early in retirement is hard to recover from.
In the bank

Savings accounts and CDs

If the market drops
Nothing changes. Deposits are FDIC-insured up to the limit.
Growth
A set rate, usually modest.
Getting to your money
Savings any time. CDs charge a penalty if you leave early.
The catch
Growth may not keep up with inflation.

In a fixed or indexed annuity

A contract with an insurance company

If the market drops
Index losses don't reduce your contract value. In a down year you're credited zero, not a loss.
Growth
A guaranteed fixed rate, or interest tied to an index up to a cap or participation rate.
Getting to your money
Many contracts let you take a portion each year. Taking more during the surrender period costs a charge.
The catch
Your upside is limited, and your money is committed for the surrender period.

Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Optional riders carry fees that can reduce your value. Annuities are not FDIC insured.

Your options, in plain English.

Four tools Michael works with. Each one fits some people well and others not at all.

Fixed indexed annuity

Interest is linked to a market index like the S&P 500, up to a cap, without your money being invested in the market.

  • Good fit if you want some growth potential without riding the market down.
  • Watch for caps, participation rates and the length of the surrender period.

Fixed annuity (MYGA)

A guaranteed interest rate for a set number of years, from an insurance company.

  • Good fit if you want a known number.
  • Watch for early-withdrawal charges.

Income for life

An annuity or income rider that turns savings into a paycheck you can't outlive.

  • Good fit if steady income matters most.
  • Watch for rider fees and what's left for heirs.
The Max Cash approach

Max-funded IUL

Indexed universal life insurance set up to hold as much cash value as tax rules allow, with the smallest death benefit those rules permit. Interest is credited based on an index, with a floor so a down year credits zero. Policy charges still come out every month, and you can borrow against the cash value later.

  • Good fit if you're healthy, can fund it for years, and want life insurance plus cash you can reach.
  • Watch for insurance charges, underfunding, and loans that can lapse a policy and create a tax bill.

How it works

One conversation to start. You decide what happens after that.

  1. Talk

    Send the form below or call. Tell Michael what the money is for and when you'll need it.

  2. Compare

    He lays out the options that fit, side by side, with the costs and surrender terms spelled out.

  3. Decide

    Take your time. Ask questions, talk it over with family, and only move if it makes sense.

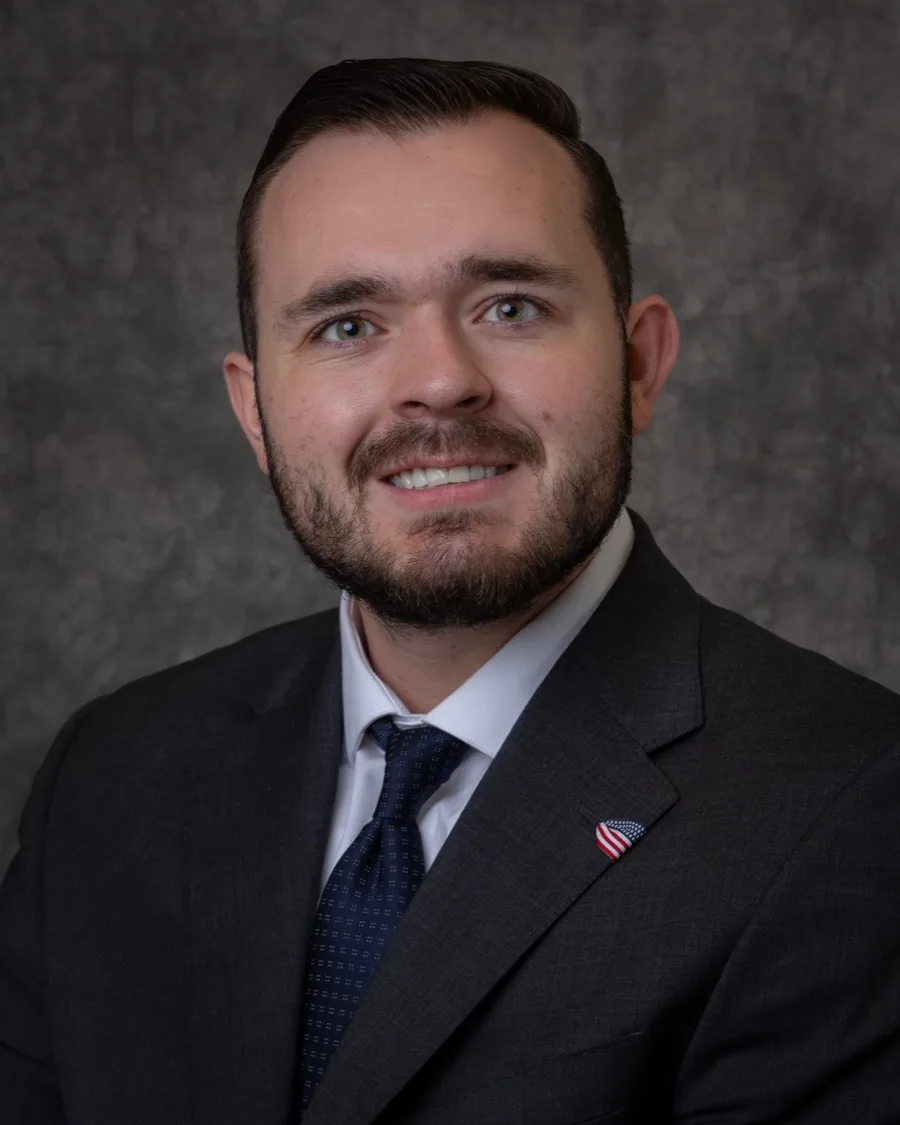
Michael Maness
Michael Maness, Licensed Insurance Producer

Meet Michael Maness

Michael is a licensed insurance producer based in Glendale, Arizona, with access to more than 30 national carriers.

Most financial products get explained with fancy terms and confusing charts. Michael does the opposite. He walks you through how each option works the way you'd explain it to a friend over coffee.

His job isn't to sell you something you don't need. It's to show you how it works and help you decide if it's right for you.
  • NPN 21767258
  • 30+ national carriers
  • Glendale, Arizona
Questions

Straight answers.

Don't see yours? Ask Michael directly. There's no such thing as a dumb question about your own money.

Talk to Michael
Does it cost anything to talk with Michael?

No. There's no fee for the conversation or the review. Like most insurance agents, Michael is paid a commission by the insurance company when a policy or annuity is issued. You don't pay him a separate fee.

Can I lose money in an annuity?

In a fixed or fixed indexed annuity, your money isn't invested in the stock market, so index drops don't reduce your contract value.

You can still come out behind if you withdraw more than the free amount during the surrender period, or if you add a rider that charges a fee. Variable annuities are different and can lose value. This site covers fixed and fixed indexed annuities.

What's a surrender period?

It's the stretch of years, set in the contract, when cashing out or taking more than the allowed free amount costs a surrender charge. The charge usually steps down each year until it's gone. Know the length before you sign.

What is a max-funded IUL?

It's indexed universal life insurance designed to take in as much premium as federal tax rules allow, with the death benefit kept as low as those rules permit. More of each dollar goes to cash value.

It's life insurance first. It has insurance costs, has to be funded as planned, and works best over many years. Policy loans and withdrawals can be income-tax-free if the policy stays in force and isn't a modified endowment contract. A lapse can create a tax bill.

Is an annuity or an IUL better?

Neither one is better across the board. An annuity is built to protect and grow savings and turn them into income. A max-funded IUL is life insurance that also builds cash value, and it needs time and health approval. Michael will walk through both with your own numbers.

Are annuities FDIC insured?

No. Annuities and life insurance are backed by the insurance company that issues them. That's why the carrier's financial strength matters, and it's one of the things Michael goes over with you.

What should I have ready?

If you already own an annuity or a policy, have your latest statement handy. Otherwise, a rough idea of your savings and when you want to retire is plenty.

Get a straight answer about your retirement money.

Tell Michael a little about what you're after and he'll get back to you. No cost, no pressure.